Washington Affordable Flood Insurance
Why buy a flood insurance? Get your affordable flood insurance through competitive rates. Protect your home with trusted provider here in Washington State. Be ready at all times!
Call our agent and get your personalized quote for free!
Primary Benefits Of Flood Insurance
As a homeowner, it is essential to understand why it is necessary to get flood insurance and the risks it poses. Flooding is an unfortunate part of life and can cause extensive damage to your home and personal belongings.
Even if you don't live in a flood zone, flooding can still be disastrous, it can result from snow melt, poor drainage systems, and constant rainfall. The best way to prevent losses from flooding is to buy flood insurance.
Building Coverage
Whether or not you should have building coverage for flood insurance depends on several factors, such as the size and structure of your home. It would be worth buying if you can replace your home when damaged during a flood.
Content Coverage/Personal Belonging
The value of your possessions is an important factor, as a small apartment or studio may require less coverage than a sprawling one-story ranch. When choosing the right coverage amount, make an inventory of all your belongings. If you don't know what you own, it may be a good idea to purchase a separate policy. Coverage limits for contents are determined by ACV, or actual cash value. This refers to the cost of repairing or replacing your belongings, less depreciation, when they are destroyed by water.
Washington Earthquake & Flood Insurance Services
You can buy flood insurance if your house has experienced flooding in the past, but there are some things to keep in mind. First, flood zones are constantly changing, and FEMA helps us ensure that we are fully protected. Determining the flood zones can be found online at the federal government's website. Even if your home isn't in a flood zone, it is still possible to experience repeated heavy rain for days on end.
Second, remember that flood insurance premiums aren't cheap. There are several options available, so make sure to shop around and compare policies. It is also important to remember that coverage has a 30-day waiting period before you can begin receiving benefits. Make sure to read everything in the fine print!
Depending on your home's location, the cost of flood insurance varies. The standard flood insurance policy covers a house up to $250,000, it doesn't cover contents over $100,000. If your home is more than this, consider purchasing an additional private policy to supplement your flood insurance. These policies can be quite expensive, so be sure to compare the different quotes from different providers.
Is Flood Insurance Worth It
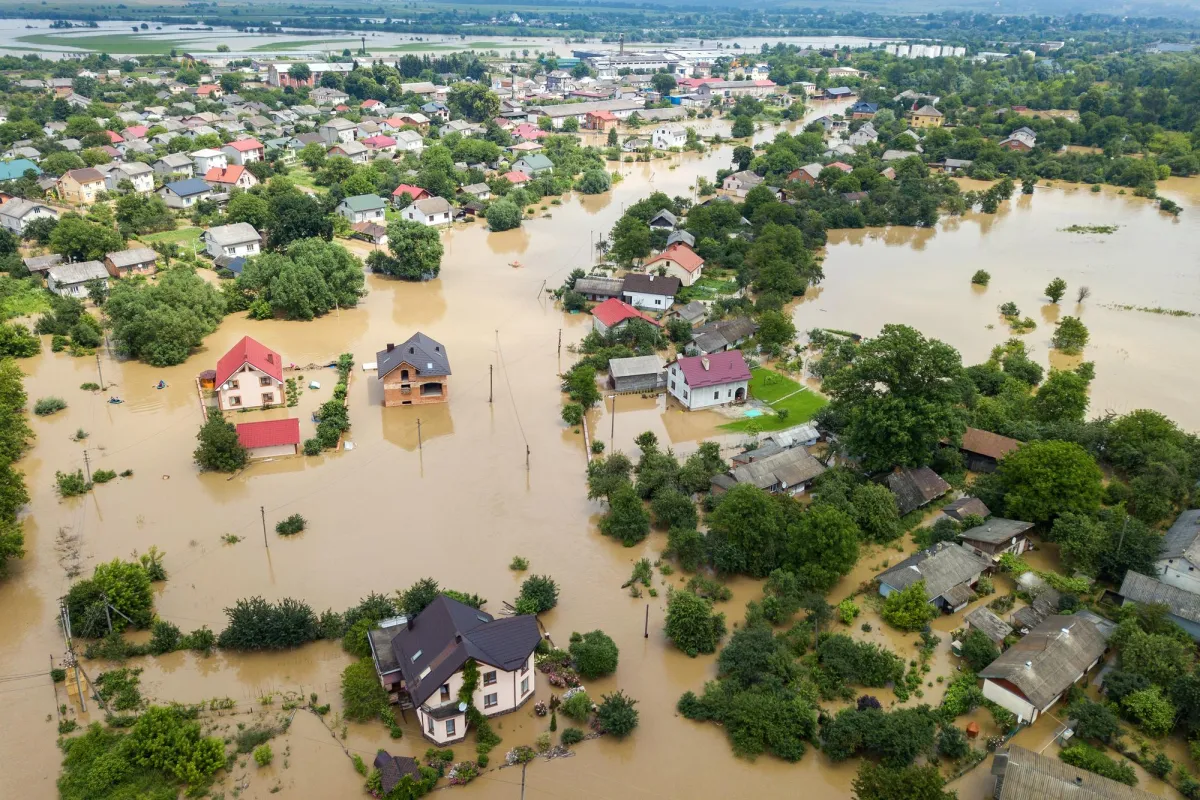
Some of you already wondering if buying flood insurance is worth it. Here are some of the reasons why this policy is worth buying. If you live in a flood-prone area consider getting one, before buying consider if you have sufficient insurance coverage. If your house does flood, you may not be able to pay to repair or replace damaged items. It is quite a bit of a responsibility to replace them with your funds. Flood insurance covers both these problems. If you think it is not important, think again and reassess your decision.
Although flood insurance isn't required by lenders, it can be a lifesaver, especially if you live near a flood zone. Flood claims are common and can cost up to $46,000. While this may seem expensive, the cost of flood insurance is negligible when you consider that one foot of water can destroy an average home. It is well worth the price of flood insurance compared to the risk of a costly flood disaster.
The US government has assisted in flood-prone areas, but much of it comes in the form of loans. Furthermore, only about half of flooding events have been declared federal disasters. So if you live in a low-risk flood zone, you may want to consider purchasing flood insurance before a storm hits. Although the cost of the policy may be prohibitive, it could be worth it if you can replace your house in the event of a flood.
The Cost Of Flood Insurance
Most places in the U.S. are at risk for flooding, the location you where will determine your premium. but where your area is at higher risk will determine your premium. Here are some tips for choosing the right flood insurance policy for your needs.
First, make sure your home is elevated. Elevating your home reduces the amount of damage it will be exposed to from floods. Second, you should make sure that your home is protected by a policy that covers your belongings.
Next, decide how much coverage you need. Flood insurance rates are typically higher for high-risk properties. If you live in one of these areas, you will want to get a policy that covers at least 80% of the home's value. You should also choose content coverage, which pays for damaged belongings at actual cash value. Average flood insurance in the U.S. is about $985 per year or $82 per month. The rates will be based depending in many factors such as your state and how much coverage you need.
To simplify things, the higher deductibles the more coverage you’ll get, which means lower premiums. If you do decide to purchase flood insurance, make sure you know how much you want to spend. It is not just a financial decision.
Flood insurance is a necessity, but it is important to take the time to do your research and make an informed decision. Always ask your insurance agent to help you with the decision-making and don’t forget to request free quotes and compare them.
Flood Insurance Experts
Flood Insurance Experts
Common Reasons For Floods
To give your more ideas on why this coverage is necessary, here are some common reasons for floods.
Tropical Storms & Hurricanes
Storms and hurricanes are powerful as well as devastating events for every community when they occur. Aside from damaging the properties, these forms of storms can bring heavy rains accompanied by high winds which may result in floods to the entire road and cities.
Heavy Rains
Constant rain can bring floods and overflow of water sewage. It can happen anytime in the year. The excess water due to flood can immediately damage anywhere it lands.
Flash Floods
Flooding from low-lying areas due to heavy rainfall is extremely dangerous and can tear up trees and destroys properties and buildings.
Mud Flows
Mudflows can add to the cause of floods which are associated with landslides and rapidly moving water to the ground. Even if your home is located on higher ground or elevated, it can be hit by mudflows.
Post Fire Conditions
Wildfires are common in the western states. Soil that has been burned cannot absorb water, meaning an increase in the risk of floods and mudflows.
Washington State, Earthquake & Flood Insurance Trusted Provider
Do you have any questions/concerns?
We work with multiple carriers for your convenience.
Comprehensive Flood & Earthquake Protection for Your Family's Peace of Mind
Washington & Seattle's Top Earthquake & Flood Insurance Specialists
News & Blogs
Struggling to Cover Retirement Expenses in Pittsburgh? How a Reverse Mortgage Could Help
Retirement should be a time to enjoy life, not constantly worry about whether there will be enough money to cover next month's expenses. Unfortunately, many Pittsburgh homeowners discover that their retirement income does not stretch as far as they expected.
Between groceries, utilities, property taxes, healthcare costs, and everyday household expenses, maintaining financial stability can become increasingly difficult. You may have spent decades building equity in your home, yet still find yourself struggling to access enough cash to manage your monthly budget.
If you are a senior homeowner experiencing this situation, a reverse mortgage may be worth exploring.
A reverse mortgage allows eligible homeowners to access a portion of their home's equity without immediately selling their property. For qualifying borrowers, this can provide another potential source of retirement funds.
Reverse Mortgage Pittsburgh offers information about several reverse mortgage options, including Home Equity Conversion Mortgages (HECMs) and proprietary reverse mortgages. Understanding how these programs work can help you decide whether exploring your home equity makes sense.
Why Pittsburgh Retirees May Be Struggling With Monthly Expenses
Retirement income can become difficult to manage when living expenses increase faster than available income.
Some homeowners experience financial pressure because of:
Rising grocery and household costs.
Increasing utility and property maintenance expenses.
Unexpected medical and prescription expenses.
Existing mortgage payments.
Credit card balances and other outstanding debt.
Reduced household income after retirement.
Even homeowners with substantial property equity may have limited cash available for immediate expenses.
This creates a difficult situation. Selling your home might provide access to money, but it could also mean leaving a familiar neighborhood and giving up the stability of your current living arrangement.
A reverse mortgage may offer another option worth investigating.
How a Reverse Mortgage Could Provide Additional Retirement Funds
A reverse mortgage is a loan secured by your home's equity. Instead of making regular principal and interest payments to a lender, qualifying borrowers receive loan proceeds according to the terms of their agreement.
With an eligible Home Equity Conversion Mortgage, homeowners generally must be at least 62 years old and meet other program requirements.
Depending on the loan, proceeds may be distributed through:
A lump-sum payment, subject to the loan's payment rules.
Monthly payments.
A line of credit.
A combination of available payment options.
The money may help cover household expenses, medical bills, home repairs, or other financial needs.
However, the amount available depends on several factors, including the borrower's age, property value, existing mortgage balance, interest rates, and loan terms.
It is also important to understand that a reverse mortgage is not free money. Interest and applicable fees increase the outstanding loan balance over time.
HECM and Proprietary Reverse Mortgage Options for Pittsburgh Homeowners
Not every reverse mortgage works the same way.
Pittsburgh homeowners researching these loans may encounter several different programs.
Home Equity Conversion Mortgage (HECM)
A HECM is the most common federally insured reverse mortgage program. It is administered through FHA insurance and generally requires borrowers to complete counseling with a HUD-approved reverse mortgage counselor.
Proprietary Reverse Mortgage
A proprietary reverse mortgage is a private loan product that is not FHA-insured. These products may be designed for homeowners with higher-value properties, depending on the lender's eligibility requirements.
Single-Purpose Reverse Mortgage
Some programs restrict how borrowers may use their loan proceeds. These programs may be offered through certain government agencies or nonprofit organizations.
Comparing these alternatives is important because eligibility, costs, available proceeds, and repayment conditions can differ.
What to Consider Before Using Home Equity for Retirement
Accessing your home's equity can provide financial flexibility, but it also creates long-term obligations.
Before proceeding, consider:
Property taxes: You remain responsible for applicable property taxes.
Homeowners insurance: Required insurance coverage must be maintained.
Home maintenance: The property must remain in acceptable condition.
Loan costs: Origination fees, interest, mortgage insurance where applicable, and closing expenses affect the total cost.
Inheritance: The growing loan balance may reduce the equity remaining for your heirs.
Future housing plans: Selling the home or permanently moving away can trigger repayment.
You should also compare a reverse mortgage against alternatives such as downsizing, refinancing, using savings, or seeking local senior assistance programs.
Speak With Reverse Mortgage Pittsburgh About Your Options
If retirement expenses are becoming difficult to manage, you do not have to make a major financial decision without understanding your alternatives.
A conversation about HECM loans, proprietary reverse mortgages, and available home equity options can help clarify whether your property may provide a potential source of retirement funds.
Contact Reverse Mortgage Pittsburgh at +1 208-409-3382 to discuss your situation and request information about available reverse mortgage options.
Understanding the numbers before committing can help you make a more informed decision about your retirement finances.
Disclaimer: This article provides general financial information only and should not be construed as financial, legal, tax, or mortgage advice. Reverse mortgage eligibility, costs, and loan terms vary. Consult a qualified mortgage professional, HUD-approved housing counselor, and appropriate financial or legal advisers before making a financial decision.
Affordable Insurance With Personal Service - Local Agents & Brokers
All Rights Reserved | Washington Earthquake & Flood Insurance
Privacy Policy | Disclaimer Terms & Conditions
Contact Us


