Washington Earthquake Insurance Coverage
An earthquake is one of the most devastating events that can happen. Your homeowners/renter’s policy will not work in the event of an earthquake. To protect yourself and your property against this, an earthquake insurance policy is specially made for this kind of disaster.
Earthquake Insurance Benefits & Coverage
Dwelling Coverage
In California, only 10% of people purchase insurance against these risks. In Washington, the number has risen to 11.3%, and in New Madrid, it has dropped to 12.7%. Dwelling coverage helps cover the home up to its included amount.
Personal Property Coverage
The furniture. computer and TV are most likely included when buying a policy. However, you can get more coverage when you buy additional breakable coverage.
Additional Living Expenses
Is the term for the expenses you incur while relocating to another location. While some homeowner's policies cover earthquake damage, many don't. Earthquake insurance can help cover the costs of temporary living expenses, such as food and hotel stays.
Cost To Remove Debris
The most likely types of homes to be damaged by an earthquake are wood-frame homes, multi-story buildings, and brick homes. Earthquake insurance can cover the cost to remove the debris damage to your property due to the earthquake.
Why Buy An Earthquake Insurance
Important questions most of our clients asked are: “Do I need an earthquake insurance policy?” To answer this is yes! Even though your house is located where earthquakes are rare, you should acquire at least the standard policy. According to a study, all 50 states in the USA are likely to experience these ground-shaking events. Most people think that the policy is expensive, however, buying coverage can cost $800 per year, this will work with $500,000 worth of coverage.
It's crucial to have this coverage because of the high possibility of earthquakes damaging your home. Most policies allow you to set a deductible of 5%, 10%, 15%, or 25% of your dwelling coverage limit. That way, you'd pay a deductible of $45,000 if your home were destroyed by an earthquake, and your insurer would pay the rest.
Earthquake insurance covers damage caused by earthquakes, volcanoes, and other seismic events. It also specifies a period for a single event. The payout will pay for repairs and replacements to your home, other structures, and personal belongings. It also covers earthquake-related land stabilization and loss-of-use coverage. This policy is beneficial for earthquake-prone areas and those with a lot of buildings made of brick, stone, or clay.
While earthquake insurance is useful for reducing losses from earthquakes, it can be very costly, especially if your home is located in a low-risk area. In such areas, some policies will not cover the full cost of repair or rebuilding, make sure to check the state and local laws before deciding to buy a policy. This can save you thousands of dollars in the long run.
What's Cover & Not?
Protect Your Investment Against Earthquake
The standard homeowner policies don't cover earthquakes. But you can add earthquake insurance as an endorsement to your policy. The coverage includes the pay—for repairs to your dwelling and any other structures attached to it. If an earthquake causes damage to your personal property, it will cover the cost to remove debris. Additionally, it may even pay for extra living expenses.
The type of insurance you purchase depends on the state where you live. For example, Californian homeowners insurance is required by law to include earthquake coverage because of the high risk of seismic earthquakes. Some states do not require to have them, however, they can help you protect against quakes. Also, earthquakes can be caused by modern disposal methods. So, earthquake insurance may be worth considering even if you live in a state with a low risk of seismic activity.
Part 1: Dwelling Coverage: Sometimes referred to as Coverage A which covers home up to included amount, but not excluded with the following:
Your homeowners’ policy limit will be the same as your earthquake insurance.
The deductibles may range between 5%, 10%, 15,%, 20%, and 25%.
Most earthquake policies excluded landscaping, pools, fences, masonry, or separate buildings.
Renting or owning a condo, does not need to buy a policy.
Part 2: Personal Property Coverage. Also known as Coverage C which covers the things inside your home, like furniture, TVs, and computers.
A $5,000 standard limit which you can increase up to $200,000.
The deductibles may range between 5%, 10%, 15,%, 20%, and 25%.
More coverage can protect you if you purchase additional breakable coverage.
Part 3: Additional Living Expenses/Loss of Use. A Coverage D provides temporary and extra costs to live somewhere else like hotels, while your house is inhabitable or being repaired.
Typically covers temporary rentals of homes, apartments, and hotel rooms, as well as restaurant meals, temporary telephone lines, furniture rental, and laundry.
The deductibles may range between 5%, 10%, 15,%, 20%, and 25%.
More coverage can protect you if you purchase additional breakable coverage.
The limit can range from $1,500 up to $100,000.
Emergency repairs coverage pays for the cost of replacing damaged items. It typically covers 5% of your dwelling and/or personal property limit. The premium will be determined depending on your deductible. Earthquake insurance deductibles will vary, but most are between ten to fifteen percent of the total rebuild value of your home. For homeowners who are concerned about their deductible, they can purchase earthquake insurance that will cover these costs.
Whether you need it or not, it is best to understand how a single event can wiped-out all of our dreams. Prevention is always better than cure, protect yourself and your assets by buying an earthquake insurance policy, which can be beneficial shortly. Or especially if you are in a high-risk quake area.
Flood Insurance Experts
Flood Insurance Experts
What Happens If My House Is Destroyed In An Earthquake Without Policy
If you are planning to buy a flood insurance policy, you should assess if your house land in a flood-prone area. Many communities can qualify for a policy through FEMA. However, if you live in an area where flood maps change frequently, you may not be able to find one without getting a quote. Vice versa, if you live in a high-risk area, you can purchase a separate policy from a private company.
A typical flood insurance policy will pay for the replacement costs of your home after a flooding event. It does not cover losses that happen before the flood. Moreover, you cannot increase the amount of coverage once the flood starts. In some areas, flood insurance is necessary, but there are also some exceptions. Generally, a flood insurance policy costs about $260 annually for a $100,000-per-inclusion limit. While this is a good start, you must ask if you need a policy.
Some areas are required to have an insurance policy by the federal government. In many cases, the insurance coverage is less than what you need, but the amount is still significant. And a flood insurance policy will provide you with peace of mind.
Washington State, Earthquake & Flood Insurance Trusted Provider
Do you have any questions/concerns?
We work with multiple carriers for your convenience.
News & Blogs
Wisdom Tooth Swelling in Spokane? Find Emergency Dental Care
Swelling near the back of your mouth can make eating, chewing, and opening your mouth uncomfortable. If the area around a wisdom tooth becomes swollen or irritated, you may be dealing with a dental problem that needs prompt professional attention.
Wisdom teeth are the last molars to emerge. When there is not enough room for them to come through properly, they can become partially trapped beneath the gums or emerge at an angle. Food and bacteria may collect around the affected area, contributing to inflammation or infection.
If you are experiencing new swelling near a wisdom tooth, do not rely on guesswork. Emergency Dental Spokane helps connect callers with licensed dental providers in Spokane and surrounding communities. Call (509) 408-3865 for assistance locating available care.
When Does a Wisdom Tooth Problem Require Urgent Attention?
Wisdom tooth complications can develop gradually or become noticeable over a short period. Some symptoms may resemble ordinary gum irritation, while others could indicate a condition requiring urgent evaluation.
Watch for warning signs such as:
Swelling or redness around the gum behind your last molar.
Tenderness when chewing or brushing near the back of your mouth.
An unpleasant taste or fluid coming from the gum.
Difficulty opening your mouth normally.
Swelling extending toward the cheek or jaw.
Food repeatedly becoming trapped around a partially erupted tooth.
These symptoms do not establish a specific diagnosis. They may be consistent with inflammation around a partially erupted wisdom tooth, tooth decay, or another dental condition.
Contact a dental professional promptly if symptoms are worsening or interfering with normal eating and oral hygiene.
Important: If you develop difficulty breathing or swallowing, rapidly spreading facial or neck swelling, or another potentially life-threatening symptom, seek emergency medical care immediately. Call 911 when appropriate rather than waiting for a dental appointment.
What Could Be Causing Swelling Around a Wisdom Tooth?
Several conditions can produce similar symptoms, so an examination is necessary to determine the cause.
1. Inflammation around a partially erupted wisdom tooth
When a wisdom tooth emerges through the gum only partly, a flap of tissue may remain over part of the tooth. Food and bacteria can collect underneath it, potentially causing inflammation known as pericoronitis.
2. Tooth decay
Wisdom teeth are often difficult to clean because of their position at the back of the mouth. Plaque buildup may contribute to decay, which can affect the tooth and surrounding tissues.
3. Gum disease or localized gum irritation
Bacteria, trapped food, and irritation around the back molars may inflame the gums. Similar symptoms can also occur when neighboring teeth or periodontal tissues are affected.
Other possibilities include an infection involving the tooth's inner tissues or a problem with an adjacent molar. Only a qualified dental professional can assess which explanation fits your symptoms.
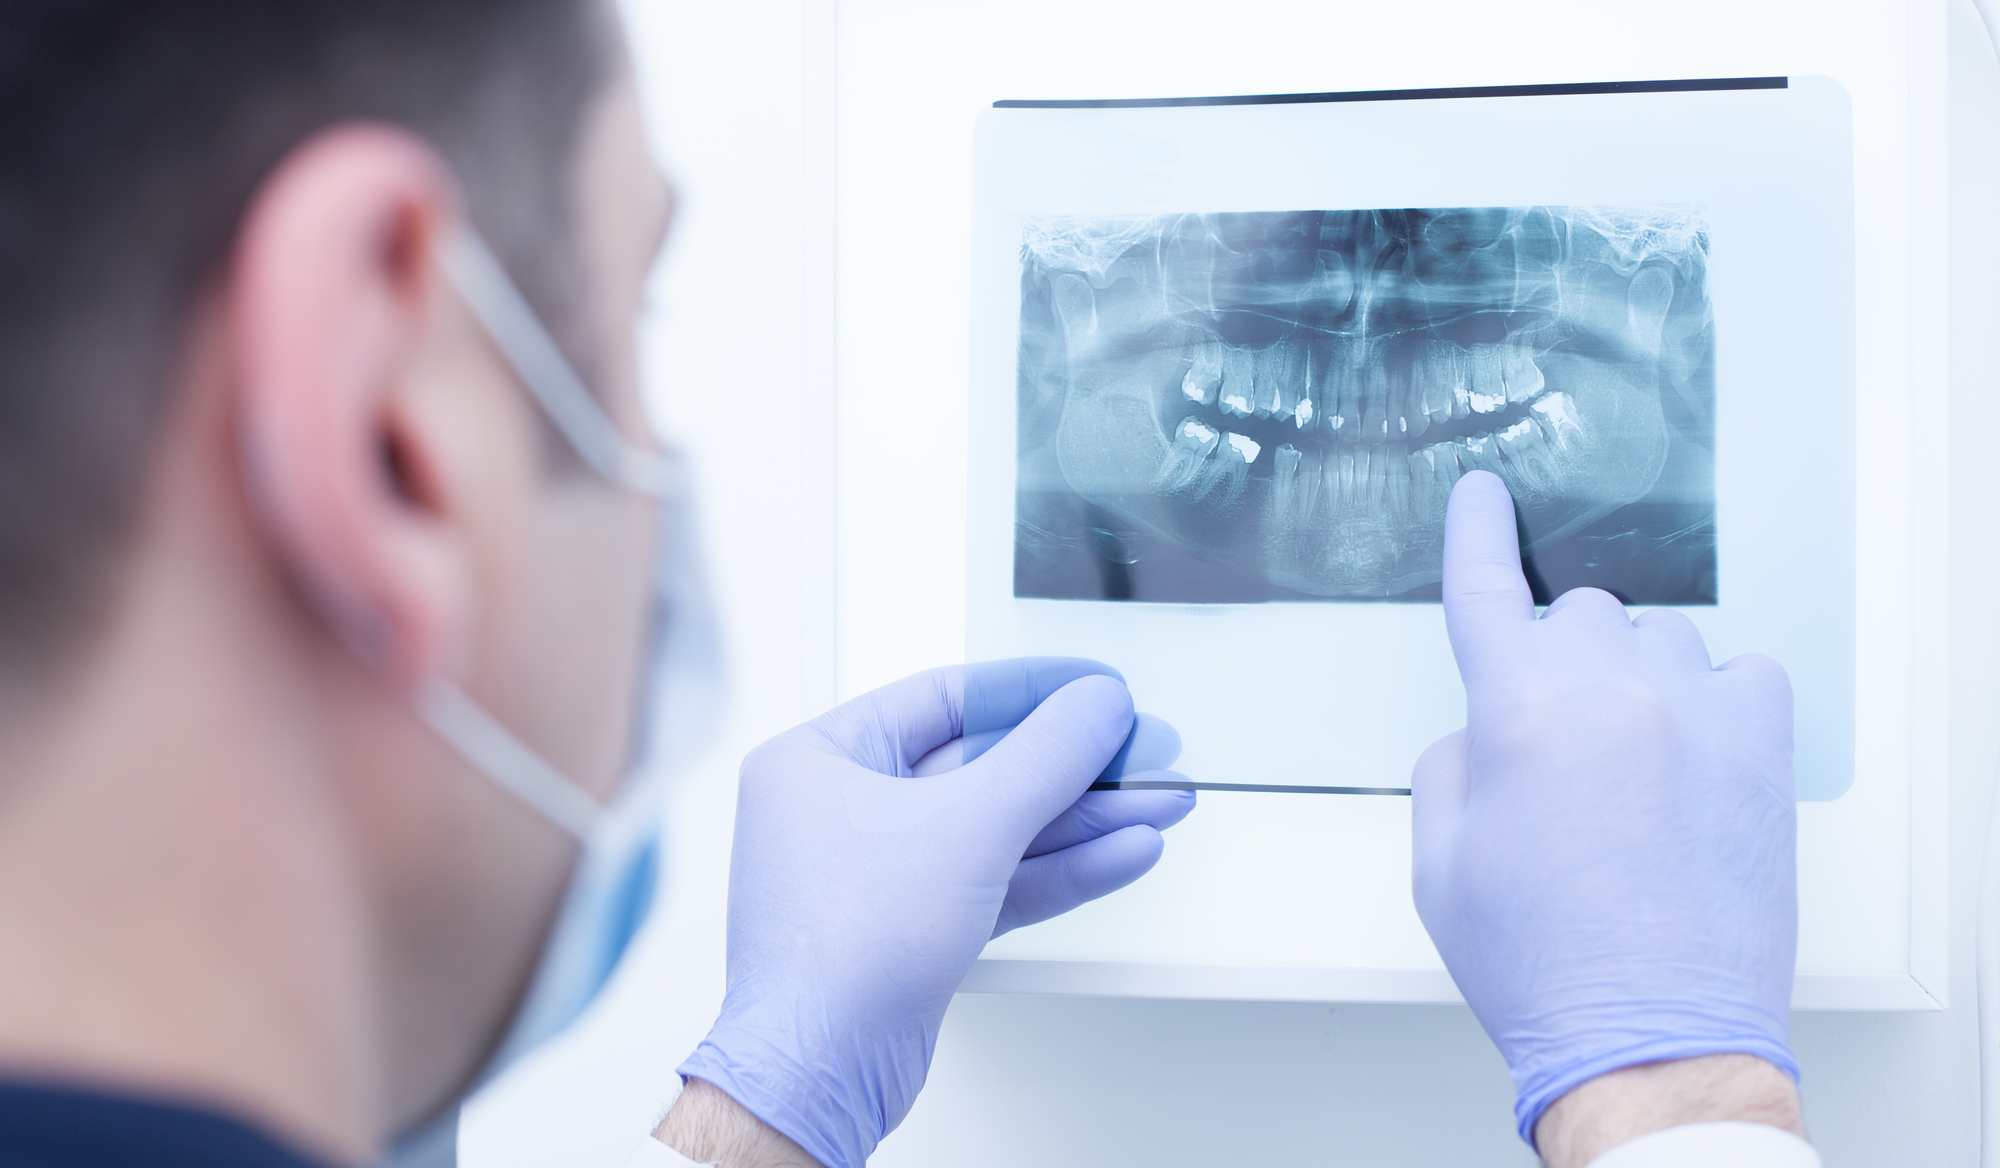
Avoid trying to diagnose the problem based on swelling alone. A dentist may examine the area and recommend dental imaging to evaluate the position of the wisdom tooth and surrounding structures.
What Treatments Might a Dentist Recommend?
Treatment depends on the cause of the swelling, the position of the tooth, and whether infection or other complications are present.
Possible treatment approaches include:
Professional cleaning and irrigation: A dentist may clean around a partially erupted tooth to remove trapped debris and assess the affected gum tissue.
Medication when indicated: A qualified provider may recommend appropriate medication when clinically necessary. Antibiotics are not required for every case of wisdom tooth inflammation and do not replace treatment of the underlying source.
Wisdom tooth extraction: If the tooth is impacted, repeatedly causes problems, or cannot be maintained appropriately, removal may be recommended.
Additional treatment for an adjacent tooth: If decay or another condition affects a neighboring molar, the dentist may recommend a filling, root canal treatment, or another appropriate procedure.
These options are not suitable for every patient. An examination helps determine whether the tooth can be monitored, needs treatment, or should be removed.
Do not attempt to cut gum tissue, drain swelling, or forcefully clean beneath the gum flap yourself.
Where Can You Find Emergency Wisdom Tooth Care in Spokane?
Searching for a provider while dealing with swelling can be frustrating, especially outside ordinary business hours.
Emergency Dental Spokane operates a phone-based appointment-coordination service that helps callers locate licensed dental providers according to availability.
The website lists coverage in:
Spokane
Spokane Valley
Liberty Lake
Airway Heights
Cheney
Medical Lake
Deer Park
Mead and Colbert
Additional nearby communities may also be served through its provider network.
When calling, explain where the swelling is located, when it began, whether you have difficulty opening your mouth, and whether the swelling is spreading. Mention any fever or difficulty swallowing so the urgency can be assessed appropriately.
Call (509) 408-3865 to request assistance finding an emergency dental provider. The service can help identify appointment options, but the actual clinic, timing, and available treatments must be confirmed.
Take the Next Step for Wisdom Tooth Swelling
Swelling around a wisdom tooth should not be ignored when it is new, persistent, or getting worse. Several dental conditions can produce similar symptoms, and professional assessment is the safest way to identify the cause and determine appropriate treatment.
If you live in Spokane, Spokane Valley, Liberty Lake, Cheney, or a nearby service area, contact Emergency Dental Spokane for help locating a provider.
Call (509) 408-3865 for assistance finding urgent dental care. If you have difficulty breathing or swallowing, seek emergency medical assistance immediately.
Disclaimer: This article provides general information only and should not be construed as professional medical or dental advice, diagnosis, or treatment. Always consult with a licensed dentist or healthcare provider regarding any dental emergency or medical condition.
Affordable Insurance With Personal Service - Local Agents & Brokers
All Rights Reserved | Washington Earthquake & Flood Insurance
Privacy Policy | Disclaimer Terms & Conditions
Contact Us


