Seattle Washington
Condo Insurance
Condominium insurance or condo insurance is built to cover any part of the building that is in your name and responsibility—including the personal property.
Contact and get your free estimate, today!
What You Need To Know About Condominium Insurance
Considering how expensive a square foot of condo property can be, you should consider getting condo insurance. When shopping for condo insurance, keep in mind that your lender may require a specific amount of coverage, so make sure to check before signing a policy.
Content Insurance
Your policy pays to replace your belongings and furniture after certain disasters. Fires and plumbing and HVAC problems are typically covered, although earthquakes are not.
Loss of Use Insurance
If your condo is damaged, it will help you pay for the costs of living in a temporary shelter until it can be fixed. The money you save will go towards repairing the damage.
Condo Liability Insurance
Condo insurance provides coverage for your medical expenses if someone gets hurt in your unit as well as legal expenses or lawsuits.
Advantage Of Buying Condo Insurance
Homeowners Associations or HOA may cover repairs or other expenses, if your unit gets damaged, however, it does not protect everything, you might need the correct type of coverage. While it is important to remember that personal property insurance has limitations and exclusions, it can pay for the costs of replacing lost or damaged items.
A standard policy will cover damage from fire, lightning, storms, theft, explosions, and other calamities. However, it won't cover earthquakes or floods. This is especially important if you live near bodies of water or in a high-risk area. The amount of coverage needed will depend on your financial situation and stage in life. Taking the time to understand your needs before buying a policy will help you get the right coverage.
Re-comparing condo insurance will help you lower your premiums. Additionally, installing smoke detectors can also end up in lower premiums. There are a lot of components where you can get lower premiums so make sure to ask your agent about it.
Flood Insurance Experts
Flood Insurance Experts
Lists Of Condo Insurance Covers
Having condo insurance means knowing the protection you’ll get. This insurance protects individual units and the bare structure of the building. It also covers fixtures, installations, and additions. In addition to covering the bare structure, and lastly the contents of a unit. It is your responsibility to purchase separate insurance policies for personal belongings, as well as for your condo's interior.
Personal Property Coverage
A condo policy provides coverage for your furniture and personal belongings in the event of fire, lightning, and hail.
Theft Protection
Theft, fire, or other covered peril will also cover these expenses. Getting coverage is a great way to protect your belonging against theft loss in your unit and also applies anywhere in the world, as well as pay for theft from your unattended car.
Special Limits Liability
Additional coverage for special or certain possessions such as money or coins and jewelry and furs.
Personal Liability Protection
It can also cover legal expenses in the event of a lawsuit or medical bills of guests if a guest is injured on your property.
Medical Payments
Moreover, some condo policies even cover your guest's medical bills if you are found responsible for a crime. For this higher coverage amounts are available if you want to increase them.
Damage To Property Of Others
Damage to someone else’s property can also and proven it is your fault and might cover under condo insurance.
Additional Living Expenses
Like many home policies, condo insurance also covers your additional living expenses when you have to move out while your unit is being repaired. Some coverage may also apply such as—loss of coverage use, meals, laundry, etc.
Theft Protection
This insurance protects individual units and the bare structure of the building. It also covers fixtures, installations, and additions. In addition to covering the bare structure, and lastly the contents of a unit.
Structures
Condo insurance may also cover common areas and buildings in addition to individual units.
Condo Insurance In Washington State
Having a Condo Insurance Policy In Washington State is vital to protect your investment. Recently, the state reformed its condominium construction laws, and now is a great time to get coverage for your investment. To get the right policy, work with an independent insurance agent. These agents work with multiple insurers to find you the best policy possible. This insurance is also known as H-06 insurance.
The policy has a few standard components, including a construction property, a liability, and a loss-of-use policy. The first two policies protect the building's structure and fixtures, while the last two protect the contents of the unit itself. In Washington State, condo insurance is not required by law, but lenders often require condo owners to have their own policy to protect their investment. Moreover, condo owners who have mortgages will have to pay into the homeowners association master insurance policy, which will cover the costs of replacing the unit.
While purchasing a condo insurance policy in Washington, it is important to compare different providers. You should look for companies that offer good service and don't rush into a decision. In addition, you should look for bundle discounts and long-term customer discounts. And always make sure to get the policy from a licensed provider, preferably with a personal insurance license. Once you have compared the prices of various companies, you will have a clear picture of which one suits your needs best.
Washington State, Earthquake & Flood Insurance Trusted Provider
Do you have any questions/concerns?
We work with multiple carriers for your convenience.
Comprehensive Flood & Earthquake Protection for Your Family's Peace of Mind
Washington & Seattle's Top Earthquake & Flood Insurance Specialists
News & Blogs
Life Insurance After a Diabetes Diagnosis in Boise: What Are Your Options?
Life Insurance After a Diabetes Diagnosis in Boise: What Are Your Options?
Receiving a diabetes diagnosis can change how you think about your financial future. Beyond managing appointments, medications, and everyday health decisions, you may begin wondering whether your family will still have access to financial protection if something happens to you.
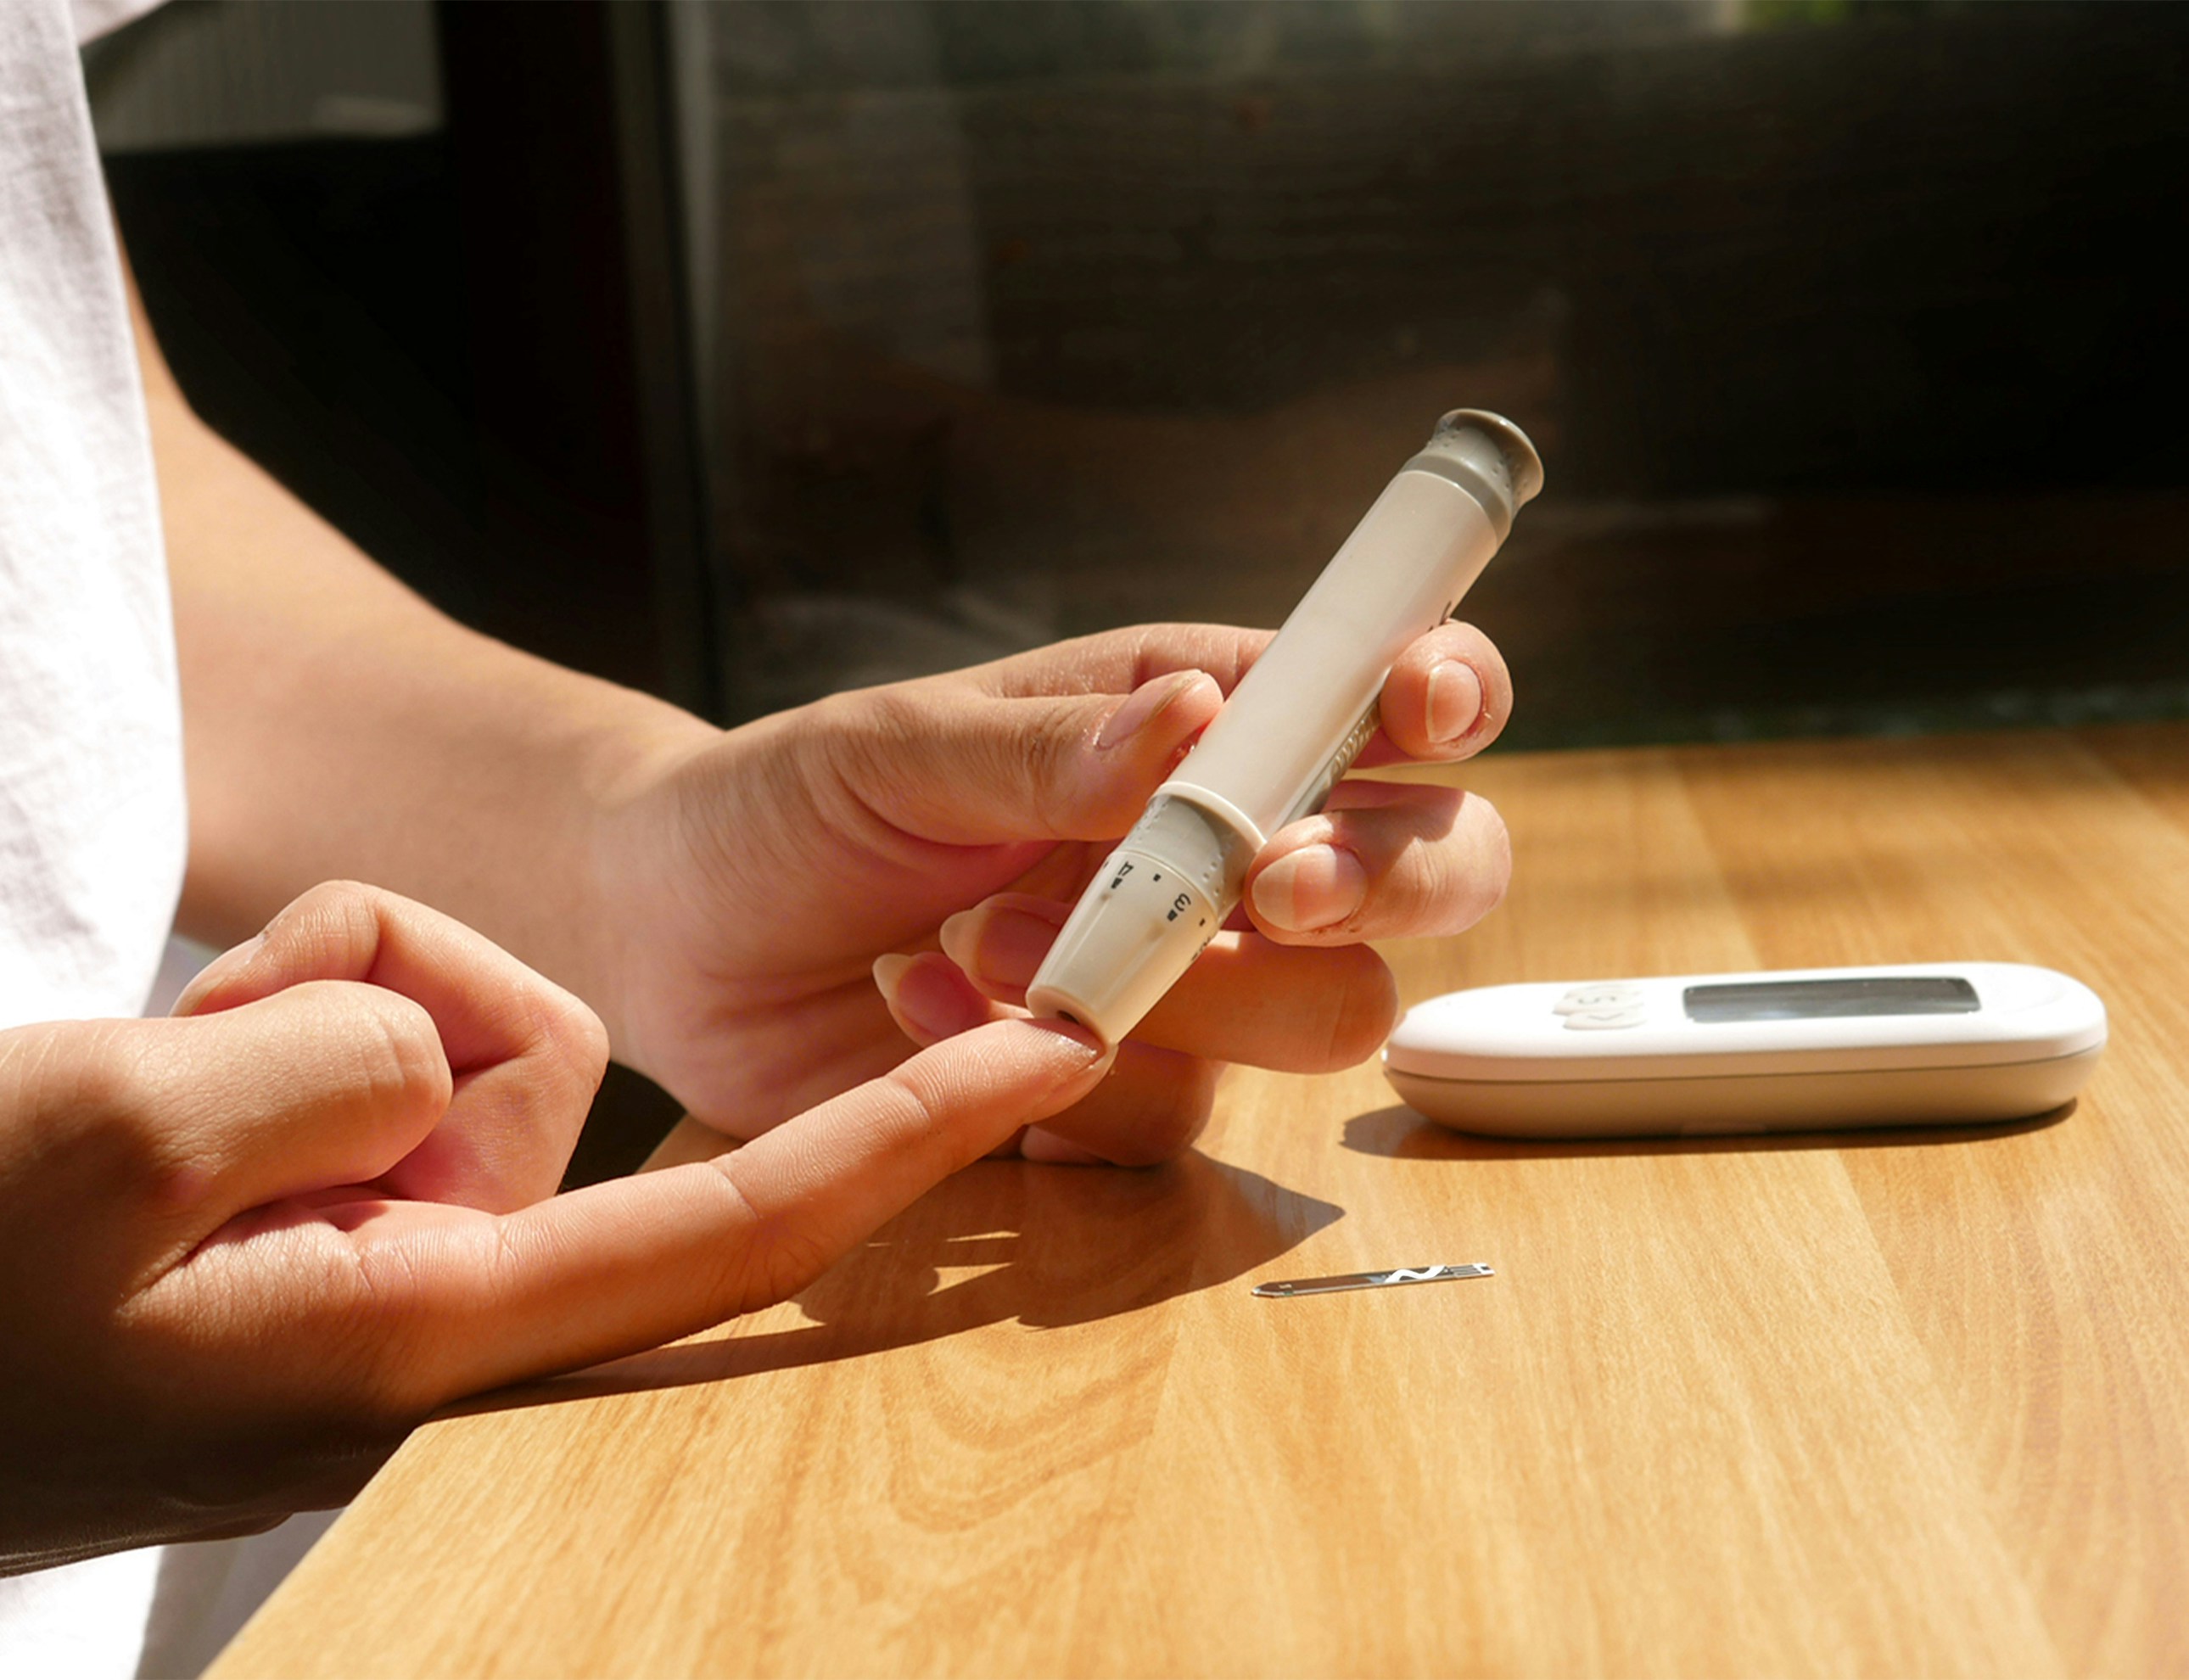
If you have recently been diagnosed with diabetes or have been managing the condition for years, you might assume that life insurance companies will automatically reject your application. That concern can become especially frustrating if you have already received an unfavorable response from an insurance provider.
However, having diabetes does not automatically mean you cannot obtain life insurance. Eligibility depends on several factors, including your type of diabetes, treatment history, overall health, and the underwriting guidelines of the insurance company.
For Boise residents looking for realistic coverage options, working with an independent agent familiar with impaired-risk underwriting can help make the process easier.
Why Diabetes Can Affect Your Life Insurance Application
Life insurance companies evaluate health information to determine the potential risk associated with providing coverage. Diabetes is one of the medical conditions that may influence underwriting decisions.
However, insurers do not necessarily evaluate every applicant with diabetes in the same way.
Some of the factors they may consider include:
Whether you have Type 1 or Type 2 diabetes.
Your age when you were diagnosed.
How consistently your condition is managed.
Your treatment history.
Whether you have experienced diabetes-related complications.
Your overall medical history.
Whether you have additional health conditions.
For example, someone with well-managed Type 2 diabetes and a consistent treatment history may receive a different underwriting assessment from someone with multiple complications.
Other factors can also influence the decision. High blood pressure, tobacco use, weight concerns, and a history of cardiovascular problems may affect how an insurer evaluates an application.
This is why it is important to avoid assuming that one insurance company's decision represents every available option.
If you live in Boise, Meridian, Nampa, Caldwell, Eagle, or another Idaho community, Chris Antrim offers guidance for people exploring life insurance with existing health conditions.
Can You Get Life Insurance With Type 1 or Type 2 Diabetes?
Yes, coverage may be possible, but the available options depend on your individual circumstances.
Type 1 and Type 2 diabetes involve different medical considerations, and insurance companies may use different underwriting guidelines for each.
For applicants with Type 1 diabetes, insurers may examine the age of diagnosis, treatment history, overall health, and whether complications have developed.
For applicants with Type 2 diabetes, companies may consider how the condition is managed, the applicant's medical history, and other risk factors.
There is no universal approval rule that applies to everyone.
An independent agent can help identify which insurance companies may be appropriate for your situation before you submit an application.
This is especially valuable when you have already received conflicting information from different providers.
Rather than applying randomly, the goal should be to understand your options and choose an application strategy that reflects your actual health history.
Three Life Insurance Options to Consider With Diabetes
Depending on your age, health, financial responsibilities, and coverage goals, several types of policies may be worth exploring.
1. Traditional Term Life Insurance
Term life insurance provides coverage for a selected period, commonly 10, 20, or 30 years.
It may be suitable for people who want to protect:
A spouse who depends on their income.
Children who still rely on financial support.
A remaining mortgage balance.
Other financial obligations that may continue for years.
Applicants with diabetes may still be considered for traditional term coverage, depending on underwriting guidelines.
2. Simplified Issue Life Insurance
Simplified issue policies generally use health questions instead of requiring a traditional medical examination.
However, these policies still have eligibility requirements, and answering the health questions does not guarantee acceptance.
They may be worth investigating when traditional underwriting appears difficult or when an applicant prefers a different application process.
3. Final Expense or Guaranteed Issue Insurance
Smaller permanent policies may provide another option for applicants who have difficulty qualifying for larger traditional coverage.
Final expense insurance can help beneficiaries manage funeral costs, outstanding bills, and other end-of-life expenses.
Guaranteed issue policies generally do not require medical underwriting in the traditional sense, but they may have limited coverage amounts, higher premiums relative to the benefit, age restrictions, and graded death benefits or waiting periods.
Understanding these limitations is essential before choosing a policy.
Why Applying Through the Right Insurance Company Matters
One of the biggest challenges for applicants with diabetes is that insurance companies do not all evaluate medical conditions identically.
One company may have underwriting guidelines that are more restrictive for a particular health profile, while another may offer a different assessment.
That difference makes carrier selection important.
Chris Antrim is an independent life insurance agent based in Boise with more than 20 years of experience in health and life insurance. His website emphasizes impaired-risk underwriting and access to multiple insurance carriers.
Instead of automatically directing every applicant toward the same policy, the process can involve reviewing the person's circumstances and identifying potentially appropriate options.
Before applying, prepare information about:
Your diabetes diagnosis and treatment history.
Your current medications.
Your recent medical records, if available.
Other diagnosed health conditions.
Your desired coverage amount.
Your monthly insurance budget.
Having this information available can make the initial discussion more productive.
What If Another Insurance Company Already Declined You?
A previous denial can be discouraging, particularly when you are trying to protect your family.
However, one company's decision does not necessarily mean every other company will reach the same conclusion.
The next step should be to understand why the application was declined.
Was the decision related to diabetes management? Were there additional medical concerns? Did the applicant select a policy with underwriting requirements that were not a good match?
These details can help determine whether another type of coverage or a different insurance company may be appropriate.
Avoid submitting multiple applications without understanding the reasons behind the previous decision. Multiple applications can create additional underwriting complications and may require you to disclose previous decisions.
An experienced independent agent can help you evaluate a more appropriate direction.
Explore Life Insurance Options With Chris Antrim in Boise
If you have diabetes and need life insurance, you do not have to assume that traditional coverage is completely out of reach.
The right approach starts with understanding your medical history, financial goals, and available insurance products.
Chris Antrim helps individuals and families throughout Boise, Meridian, Eagle, Kuna, Star, Nampa, Caldwell, and other Idaho communities explore life insurance options, including coverage for people with existing health conditions.
Call or text Chris Antrim at (425) 761-0555 to discuss your circumstances and explore potential coverage options.
You can also learn more about the impaired-risk life insurance services available through the website.
You deserve a clear explanation of your choices before making an important financial decision.

Affordable Insurance With Personal Service - Local Agents & Brokers
All Rights Reserved | Washington Earthquake & Flood Insurance
Privacy Policy | Disclaimer Terms & Conditions
Contact Us


