Washington Earthquake & Flood Insurance Agents
If you're looking for earthquake insurance, we have good news! It's available as a separate endorsement alongside your standard homeowners or renters policy. However, it's important to note that this coverage typically doesn't include damage from floods or tidal waves, even if they're related to the earthquake.
To protect your home and belongings in the event of a flood, many providers offer separate flood insurance policies. At our agency, we have experienced agents and brokers who can help you find the perfect policy at an affordable premium. Give us a call today at 206-759-2566 for a quote and start saving money! We proudly serve Washington, Seattle, Tacoma, and Puget Sound.
We're excited to assist you!
Helping Homeowners & Businesses Protect Their Investments By Finding the Right Earthquake & Flood Insurance Policy
Washington Flood & Quake Insurance Experts
Multi Company Quotes & Comparisons
Competitive Pricing Affordable Plans
Customer-Focused
Business Analysis & Audit
Washington Earthquake & Flood Insurance Services
As your insurance provider and specialist, we ensure that you receive a good quality of services. We provide reliable and professional services to meet all your needs.

Earthquake Insurance
As a homeowner, you can now rest easy knowing that you and your abode are safeguarded against any calamities that may arise from earthquakes, volcanic eruptions, and other natural disasters. Our insurance policy provides coverage for any damages to your home, car, and other structures that may result from earthquakes. In addition, you can be assured that any uncertainty arising from such disasters will be taken care of by our comprehensive earthquake insurance policy.
Flood Insurance
As a homeowner, it's crucial to invest in the right insurance policy to safeguard your investment. Flood insurance is a specialized type of home insurance that covers damages caused by external flooding. It's a cost-effective way to protect your home and belongings from potential water damage. Moreover, flood insurance provides comprehensive coverage for your possessions, which is a valuable addition to your standard home insurance policy.
Homeowner Insurance
Homeowners insurance is a crucial aspect of homeownership that offers security and peace of mind to homeowners. It provides protection against unexpected damages and theft that could potentially occur within your private residence. This type of insurance is commonly referred to as homeowners insurance and is widely utilized across the United States. It is a fundamental component of homeownership as it helps to safeguard one of your most valuable assets, your home.
Earthquake Insurance
Protect your Seattle condo with comprehensive insurance coverage tailored to your needs. Our condo insurance policies safeguard your unit, belongings, and liability, giving you peace of mind in the heart of the Pacific Northwest. Whether you're in downtown Seattle, Capitol Hill, or Queen Anne, we offer competitive rates and personalized service.
Homeowner Insurance
Affordable renters insurance in Seattle, WA, designed to protect your belongings and provide peace of mind. Whether you’re renting in Capitol Hill, Ballard, or Downtown, our policies cover theft, fire, water damage, and liability. Get a fast, hassle-free quote and ensure your possessions are protected in the Emerald City. Secure your home today with reliable renters insurance!
Washington Earthquake & Flood Insurance Services
Earthquakes and floods are one of the most intense and frightening events that could ruin everything in just one wipe. Extreme movement and ground shaking can result in massive destruction to every building and ground. A sudden shake can also trigger an underwater event called a tsunami. These extraordinarily long and giant waves can also be an event of destruction if they reach the shore and land.
Flooding occurs anywhere, along with heavy rain, snow melt, and poor drainage systems. You can minimize the damage of overflowing water by buying a policy covering these two dramatic events. We all know that your standard homeowners' or renters' policies cannot cover these certain losses. To protect yourself and your property, you can purchase a separate earthquake and flood insurance coverage policy. We won't let these two ruin everything from the ground.
Houses and business buildings are generally required to buy a flood policy within a high-risk flood area. Damages or losses due to landslides, settlements, mudflow, or rising and sinking of the earth might cover the damage if proven made from an earthquake.
The rates vary on the location and the risk of an earthquake. The cost of earthquake insurance typically offers a high deductible, which can be beneficial if the entire house when destroyed, unlike if the house is merely damaged. In addition, rates may differ and be cheaper for homes made of wood, which is a greater chance to survive than houses made of stone/brick.
Understanding Earthquake & Flood Insurance—Who Should Get A Coverage
Earthquake and flood policy is different from each other as well as provide additional coverage. However, both of them protect certain events. Your earthquake policy can cover your home coverage, living expenses, personal expenses, and sometimes more, depending on the type of policy you get. At the same time, flood insurance can help cover the devastating damage to your home's structure and content.
There are several reasons why it is a must-have coverage. For starters, it will cover the costs of damages and rebuilding your property after an earthquake. Increasing your deductibles helps you lower your monthly premiums. Additionally, you can save money by getting a policy in an area less prone to earthquakes because it is a good idea to get a quote before buying an earthquake policy.
To give you more ideas about the policy, you can consult an expert to help you assess your area's risk.
Moreover, you should consider purchasing an earthquake insurance policy if you live in an area where fracking is prevalent. California, Texas, and Oklahoma are known for having high earthquake risks. Before getting coverage, remember that the policy should cover the entire rebuilding costs of your home, not just the market value. Make sure to understand the complete form of coverage since it constitutes the cost of construction materials such as labor.
Another important consideration when getting coverage is whether you need flood protection. As we mentioned, constant ground shaking might result in a tsunami which can lead to a flood. In addition to paying for replacement materials for your home, earthquake insurance can also pay for additional living expenses.
Flood Insurance Experts
Flood Insurance Experts
Is Flood Insurance Policy Required
If you are planning to buy a flood insurance policy, you should assess if your house land in a flood-prone area. Many communities can qualify for a policy through FEMA. However, if you live in an area where flood maps change frequently, you may not be able to find one without getting a quote. Vice versa, if you live in a high-risk area, you can purchase a separate policy from a private company.
A typical flood insurance policy will pay for the replacement costs of your home after a flooding event. It does not cover losses that happen before the flood. Moreover, you cannot increase the amount of coverage once the flood starts. In some areas, flood insurance is necessary, but there are also some exceptions. Generally, a flood insurance policy costs about $260 annually for a $100,000-per-inclusion limit. While this is a good start, you must ask if you need a policy.
Some areas are required to have an insurance policy by the federal government. In many cases, the insurance coverage is less than what you need, but the amount is still significant. And a flood insurance policy will provide you with peace of mind.
Is Flood Insurance Policy Required
The USA consists of 50 states, and 16 face the world's highest seismic risks. Although the country divides into four major earthquake zones, all 50 states will likely experience damaging ground shaking within the next 50 years.
California, the Pacific Northwest, and the Intermountain West are most at risk of shaking. The New Madrid Seismic Zone runs through the center of the country, near cities such as Charleston, South Carolina.
The U.S. Geological Survey has updated its maps several times, indicating that the western U.S. is at a higher risk of earthquakes. Insurance companies and influence heavily rely on the maps, worth billions of dollars in construction each year.
In addition, by updating the United States' earthquake maps. There are new data from the USGS and UCERF3, which helps us better understand how much seismic risk each area faces. These new updates give ideas about the shakes, fire-following, and liquefaction components, as well as tsunami and landslide sub-peril.
This information and the new model can help us better protect our communities from earthquakes.
Washington State, Earthquake & Flood Insurance Trusted Provider
Do you have any questions/concerns?
We work with multiple carriers for your convenience.
Comprehensive Flood & Earthquake Protection for Your Family's Peace of Mind
Washington & Seattle's Top Earthquake & Flood Insurance Specialists
News & Blogs
Life Insurance After a Diabetes Diagnosis in Boise: What Are Your Options?
Life Insurance After a Diabetes Diagnosis in Boise: What Are Your Options?
Receiving a diabetes diagnosis can change how you think about your financial future. Beyond managing appointments, medications, and everyday health decisions, you may begin wondering whether your family will still have access to financial protection if something happens to you.
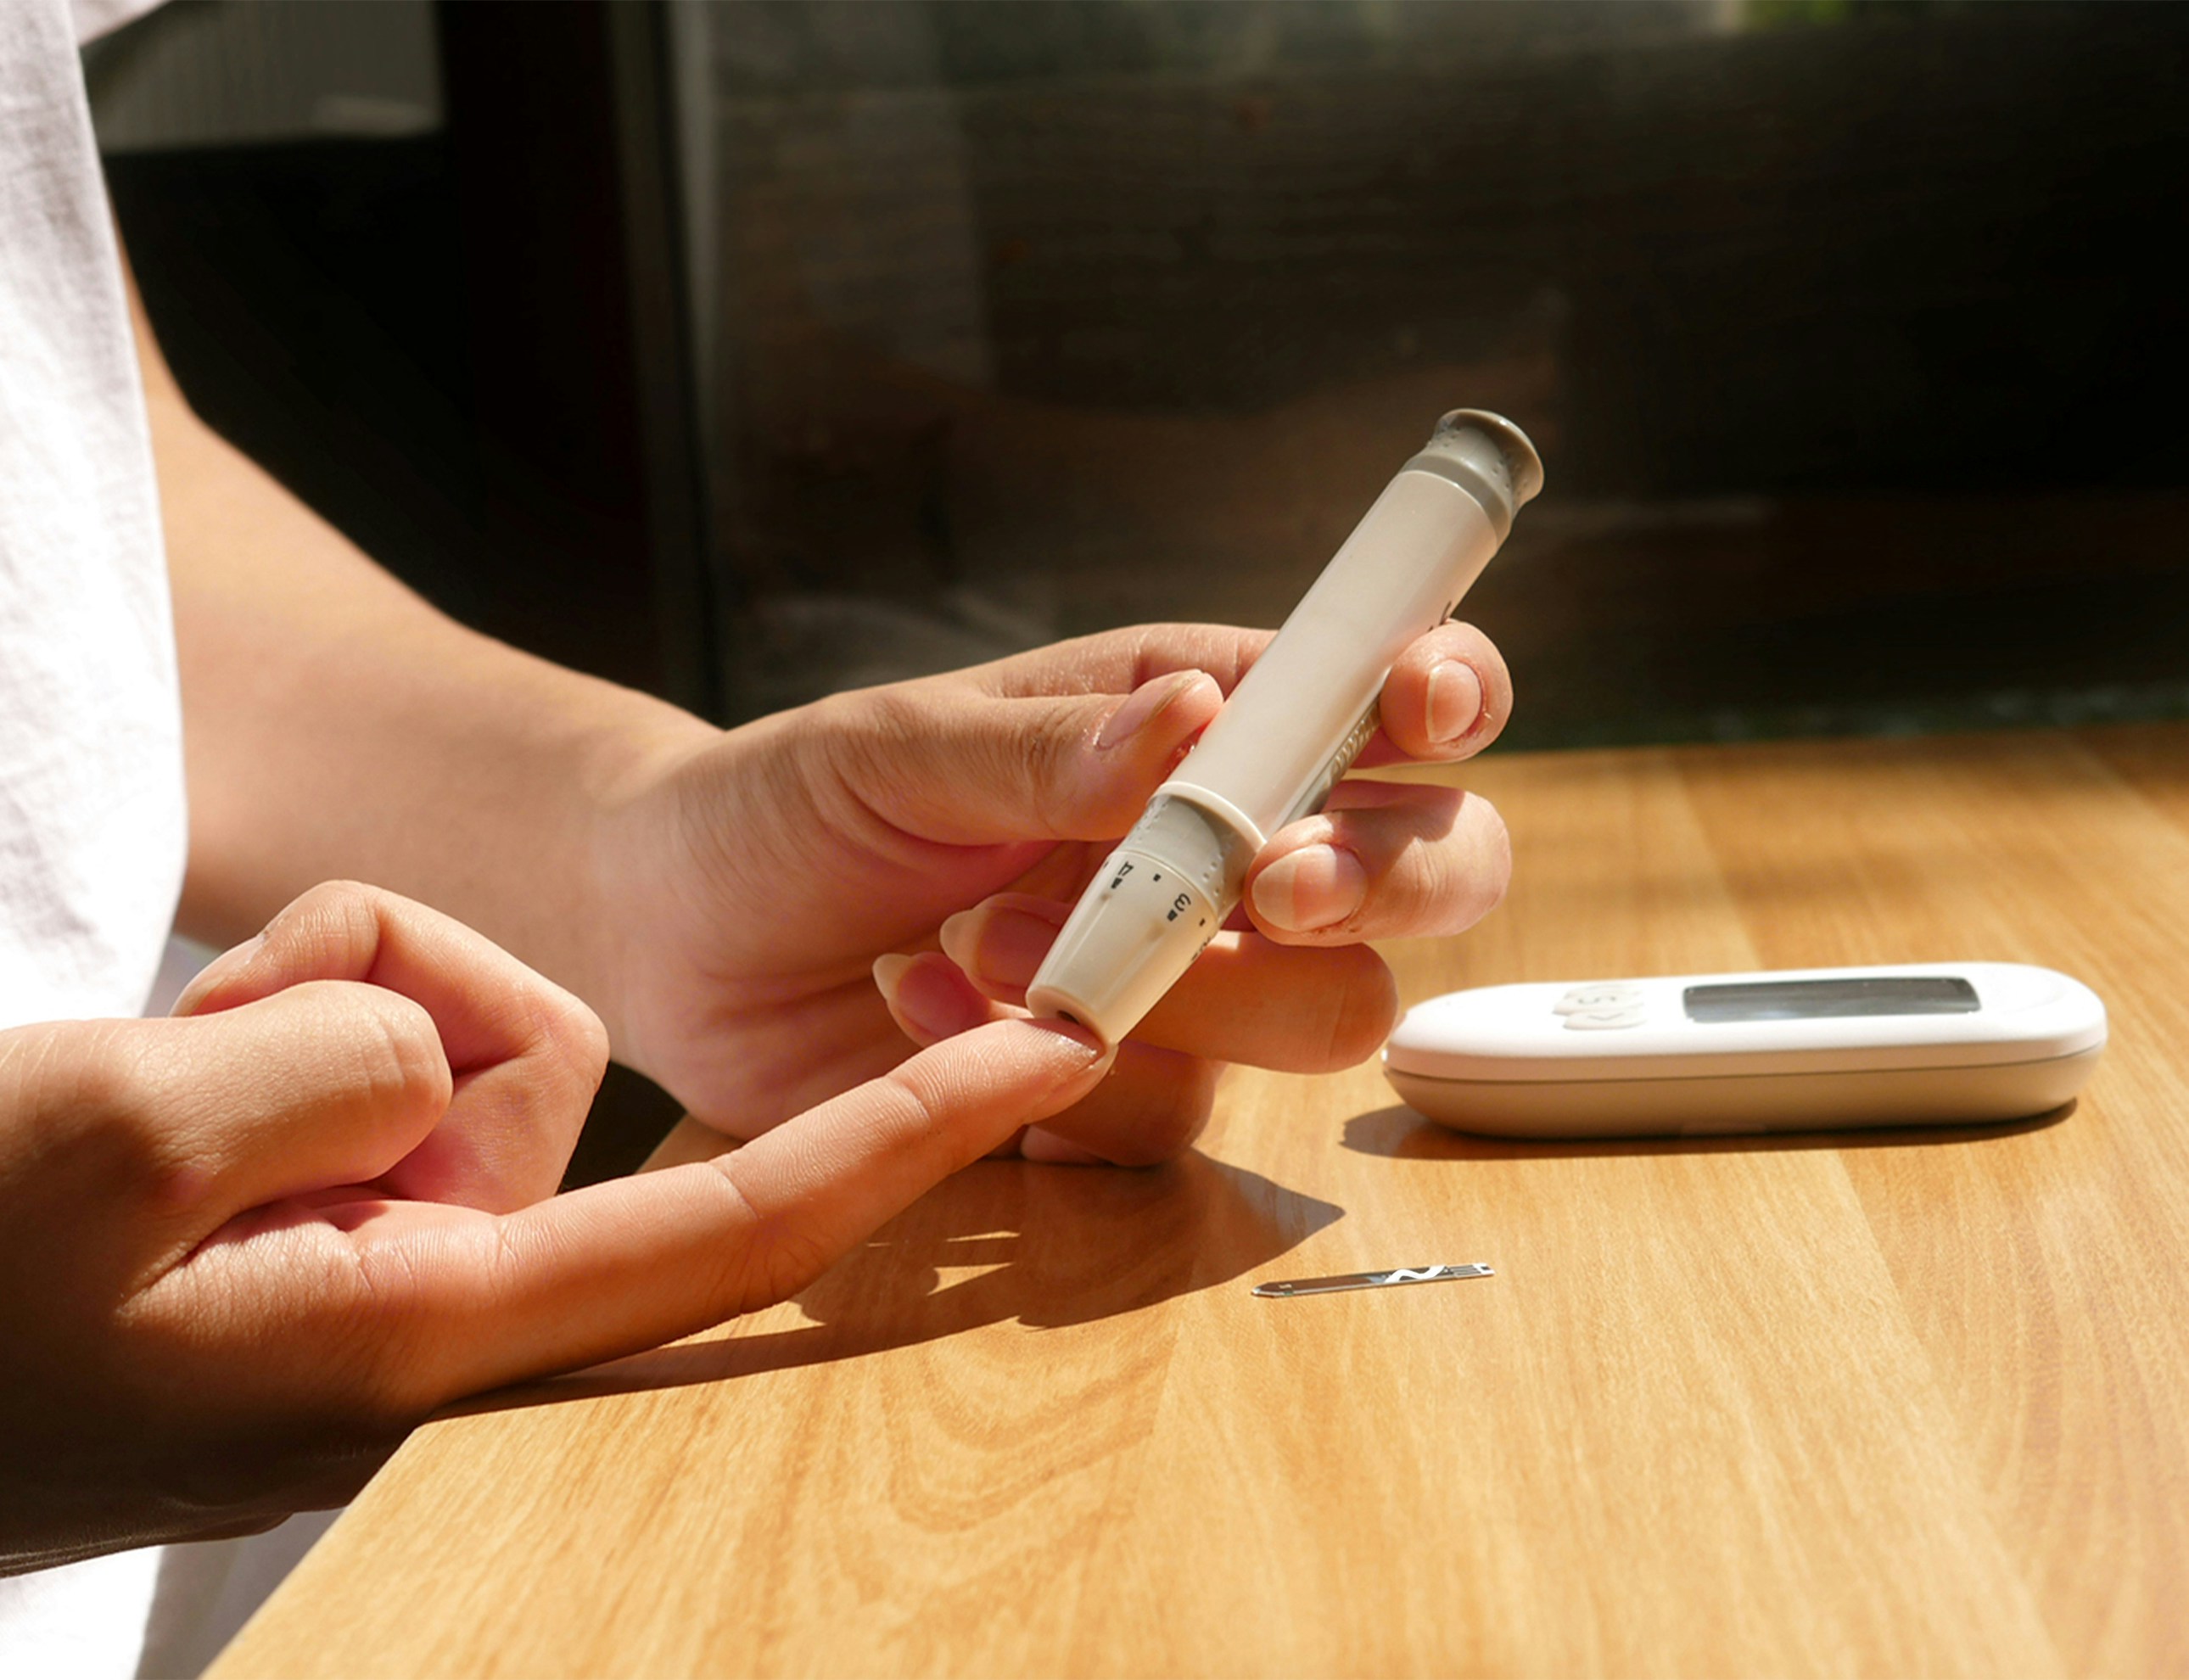
If you have recently been diagnosed with diabetes or have been managing the condition for years, you might assume that life insurance companies will automatically reject your application. That concern can become especially frustrating if you have already received an unfavorable response from an insurance provider.
However, having diabetes does not automatically mean you cannot obtain life insurance. Eligibility depends on several factors, including your type of diabetes, treatment history, overall health, and the underwriting guidelines of the insurance company.
For Boise residents looking for realistic coverage options, working with an independent agent familiar with impaired-risk underwriting can help make the process easier.
Why Diabetes Can Affect Your Life Insurance Application
Life insurance companies evaluate health information to determine the potential risk associated with providing coverage. Diabetes is one of the medical conditions that may influence underwriting decisions.
However, insurers do not necessarily evaluate every applicant with diabetes in the same way.
Some of the factors they may consider include:
Whether you have Type 1 or Type 2 diabetes.
Your age when you were diagnosed.
How consistently your condition is managed.
Your treatment history.
Whether you have experienced diabetes-related complications.
Your overall medical history.
Whether you have additional health conditions.
For example, someone with well-managed Type 2 diabetes and a consistent treatment history may receive a different underwriting assessment from someone with multiple complications.
Other factors can also influence the decision. High blood pressure, tobacco use, weight concerns, and a history of cardiovascular problems may affect how an insurer evaluates an application.
This is why it is important to avoid assuming that one insurance company's decision represents every available option.
If you live in Boise, Meridian, Nampa, Caldwell, Eagle, or another Idaho community, Chris Antrim offers guidance for people exploring life insurance with existing health conditions.
Can You Get Life Insurance With Type 1 or Type 2 Diabetes?
Yes, coverage may be possible, but the available options depend on your individual circumstances.
Type 1 and Type 2 diabetes involve different medical considerations, and insurance companies may use different underwriting guidelines for each.
For applicants with Type 1 diabetes, insurers may examine the age of diagnosis, treatment history, overall health, and whether complications have developed.
For applicants with Type 2 diabetes, companies may consider how the condition is managed, the applicant's medical history, and other risk factors.
There is no universal approval rule that applies to everyone.
An independent agent can help identify which insurance companies may be appropriate for your situation before you submit an application.
This is especially valuable when you have already received conflicting information from different providers.
Rather than applying randomly, the goal should be to understand your options and choose an application strategy that reflects your actual health history.
Three Life Insurance Options to Consider With Diabetes
Depending on your age, health, financial responsibilities, and coverage goals, several types of policies may be worth exploring.
1. Traditional Term Life Insurance
Term life insurance provides coverage for a selected period, commonly 10, 20, or 30 years.
It may be suitable for people who want to protect:
A spouse who depends on their income.
Children who still rely on financial support.
A remaining mortgage balance.
Other financial obligations that may continue for years.
Applicants with diabetes may still be considered for traditional term coverage, depending on underwriting guidelines.
2. Simplified Issue Life Insurance
Simplified issue policies generally use health questions instead of requiring a traditional medical examination.
However, these policies still have eligibility requirements, and answering the health questions does not guarantee acceptance.
They may be worth investigating when traditional underwriting appears difficult or when an applicant prefers a different application process.
3. Final Expense or Guaranteed Issue Insurance
Smaller permanent policies may provide another option for applicants who have difficulty qualifying for larger traditional coverage.
Final expense insurance can help beneficiaries manage funeral costs, outstanding bills, and other end-of-life expenses.
Guaranteed issue policies generally do not require medical underwriting in the traditional sense, but they may have limited coverage amounts, higher premiums relative to the benefit, age restrictions, and graded death benefits or waiting periods.
Understanding these limitations is essential before choosing a policy.
Why Applying Through the Right Insurance Company Matters
One of the biggest challenges for applicants with diabetes is that insurance companies do not all evaluate medical conditions identically.
One company may have underwriting guidelines that are more restrictive for a particular health profile, while another may offer a different assessment.
That difference makes carrier selection important.
Chris Antrim is an independent life insurance agent based in Boise with more than 20 years of experience in health and life insurance. His website emphasizes impaired-risk underwriting and access to multiple insurance carriers.
Instead of automatically directing every applicant toward the same policy, the process can involve reviewing the person's circumstances and identifying potentially appropriate options.
Before applying, prepare information about:
Your diabetes diagnosis and treatment history.
Your current medications.
Your recent medical records, if available.
Other diagnosed health conditions.
Your desired coverage amount.
Your monthly insurance budget.
Having this information available can make the initial discussion more productive.
What If Another Insurance Company Already Declined You?
A previous denial can be discouraging, particularly when you are trying to protect your family.
However, one company's decision does not necessarily mean every other company will reach the same conclusion.
The next step should be to understand why the application was declined.
Was the decision related to diabetes management? Were there additional medical concerns? Did the applicant select a policy with underwriting requirements that were not a good match?
These details can help determine whether another type of coverage or a different insurance company may be appropriate.
Avoid submitting multiple applications without understanding the reasons behind the previous decision. Multiple applications can create additional underwriting complications and may require you to disclose previous decisions.
An experienced independent agent can help you evaluate a more appropriate direction.
Explore Life Insurance Options With Chris Antrim in Boise
If you have diabetes and need life insurance, you do not have to assume that traditional coverage is completely out of reach.
The right approach starts with understanding your medical history, financial goals, and available insurance products.
Chris Antrim helps individuals and families throughout Boise, Meridian, Eagle, Kuna, Star, Nampa, Caldwell, and other Idaho communities explore life insurance options, including coverage for people with existing health conditions.
Call or text Chris Antrim at (425) 761-0555 to discuss your circumstances and explore potential coverage options.
You can also learn more about the impaired-risk life insurance services available through the website.
You deserve a clear explanation of your choices before making an important financial decision.

Affordable Insurance With Personal Service - Local Agents & Brokers
All Rights Reserved | Washington Earthquake & Flood Insurance
Privacy Policy | Disclaimer Terms & Conditions
Contact Us


