Washington Earthquake & Flood Insurance Agents
If you're looking for earthquake insurance, we have good news! It's available as a separate endorsement alongside your standard homeowners or renters policy. However, it's important to note that this coverage typically doesn't include damage from floods or tidal waves, even if they're related to the earthquake.
To protect your home and belongings in the event of a flood, many providers offer separate flood insurance policies. At our agency, we have experienced agents and brokers who can help you find the perfect policy at an affordable premium. Give us a call today at 206-759-2566 for a quote and start saving money! We proudly serve Washington, Seattle, Tacoma, and Puget Sound.
We're excited to assist you!
Helping Homeowners & Businesses Protect Their Investments By Finding the Right Earthquake & Flood Insurance Policy
Washington Flood & Quake Insurance Experts
Multi Company Quotes & Comparisons
Competitive Pricing Affordable Plans
Customer-Focused
Business Analysis & Audit
Washington Earthquake & Flood Insurance Services
As your insurance provider and specialist, we ensure that you receive a good quality of services. We provide reliable and professional services to meet all your needs.

Earthquake Insurance
As a homeowner, you can now rest easy knowing that you and your abode are safeguarded against any calamities that may arise from earthquakes, volcanic eruptions, and other natural disasters. Our insurance policy provides coverage for any damages to your home, car, and other structures that may result from earthquakes. In addition, you can be assured that any uncertainty arising from such disasters will be taken care of by our comprehensive earthquake insurance policy.
Flood Insurance
As a homeowner, it's crucial to invest in the right insurance policy to safeguard your investment. Flood insurance is a specialized type of home insurance that covers damages caused by external flooding. It's a cost-effective way to protect your home and belongings from potential water damage. Moreover, flood insurance provides comprehensive coverage for your possessions, which is a valuable addition to your standard home insurance policy.
Homeowner Insurance
Homeowners insurance is a crucial aspect of homeownership that offers security and peace of mind to homeowners. It provides protection against unexpected damages and theft that could potentially occur within your private residence. This type of insurance is commonly referred to as homeowners insurance and is widely utilized across the United States. It is a fundamental component of homeownership as it helps to safeguard one of your most valuable assets, your home.
Earthquake Insurance
Protect your Seattle condo with comprehensive insurance coverage tailored to your needs. Our condo insurance policies safeguard your unit, belongings, and liability, giving you peace of mind in the heart of the Pacific Northwest. Whether you're in downtown Seattle, Capitol Hill, or Queen Anne, we offer competitive rates and personalized service.
Homeowner Insurance
Affordable renters insurance in Seattle, WA, designed to protect your belongings and provide peace of mind. Whether you’re renting in Capitol Hill, Ballard, or Downtown, our policies cover theft, fire, water damage, and liability. Get a fast, hassle-free quote and ensure your possessions are protected in the Emerald City. Secure your home today with reliable renters insurance!
Washington Earthquake & Flood Insurance Services
Earthquakes and floods are one of the most intense and frightening events that could ruin everything in just one wipe. Extreme movement and ground shaking can result in massive destruction to every building and ground. A sudden shake can also trigger an underwater event called a tsunami. These extraordinarily long and giant waves can also be an event of destruction if they reach the shore and land.
Flooding occurs anywhere, along with heavy rain, snow melt, and poor drainage systems. You can minimize the damage of overflowing water by buying a policy covering these two dramatic events. We all know that your standard homeowners' or renters' policies cannot cover these certain losses. To protect yourself and your property, you can purchase a separate earthquake and flood insurance coverage policy. We won't let these two ruin everything from the ground.
Houses and business buildings are generally required to buy a flood policy within a high-risk flood area. Damages or losses due to landslides, settlements, mudflow, or rising and sinking of the earth might cover the damage if proven made from an earthquake.
The rates vary on the location and the risk of an earthquake. The cost of earthquake insurance typically offers a high deductible, which can be beneficial if the entire house when destroyed, unlike if the house is merely damaged. In addition, rates may differ and be cheaper for homes made of wood, which is a greater chance to survive than houses made of stone/brick.
Understanding Earthquake & Flood Insurance—Who Should Get A Coverage
Earthquake and flood policy is different from each other as well as provide additional coverage. However, both of them protect certain events. Your earthquake policy can cover your home coverage, living expenses, personal expenses, and sometimes more, depending on the type of policy you get. At the same time, flood insurance can help cover the devastating damage to your home's structure and content.
There are several reasons why it is a must-have coverage. For starters, it will cover the costs of damages and rebuilding your property after an earthquake. Increasing your deductibles helps you lower your monthly premiums. Additionally, you can save money by getting a policy in an area less prone to earthquakes because it is a good idea to get a quote before buying an earthquake policy.
To give you more ideas about the policy, you can consult an expert to help you assess your area's risk.
Moreover, you should consider purchasing an earthquake insurance policy if you live in an area where fracking is prevalent. California, Texas, and Oklahoma are known for having high earthquake risks. Before getting coverage, remember that the policy should cover the entire rebuilding costs of your home, not just the market value. Make sure to understand the complete form of coverage since it constitutes the cost of construction materials such as labor.
Another important consideration when getting coverage is whether you need flood protection. As we mentioned, constant ground shaking might result in a tsunami which can lead to a flood. In addition to paying for replacement materials for your home, earthquake insurance can also pay for additional living expenses.
Flood Insurance Experts
Flood Insurance Experts
Is Flood Insurance Policy Required
If you are planning to buy a flood insurance policy, you should assess if your house land in a flood-prone area. Many communities can qualify for a policy through FEMA. However, if you live in an area where flood maps change frequently, you may not be able to find one without getting a quote. Vice versa, if you live in a high-risk area, you can purchase a separate policy from a private company.
A typical flood insurance policy will pay for the replacement costs of your home after a flooding event. It does not cover losses that happen before the flood. Moreover, you cannot increase the amount of coverage once the flood starts. In some areas, flood insurance is necessary, but there are also some exceptions. Generally, a flood insurance policy costs about $260 annually for a $100,000-per-inclusion limit. While this is a good start, you must ask if you need a policy.
Some areas are required to have an insurance policy by the federal government. In many cases, the insurance coverage is less than what you need, but the amount is still significant. And a flood insurance policy will provide you with peace of mind.
Is Flood Insurance Policy Required
The USA consists of 50 states, and 16 face the world's highest seismic risks. Although the country divides into four major earthquake zones, all 50 states will likely experience damaging ground shaking within the next 50 years.
California, the Pacific Northwest, and the Intermountain West are most at risk of shaking. The New Madrid Seismic Zone runs through the center of the country, near cities such as Charleston, South Carolina.
The U.S. Geological Survey has updated its maps several times, indicating that the western U.S. is at a higher risk of earthquakes. Insurance companies and influence heavily rely on the maps, worth billions of dollars in construction each year.
In addition, by updating the United States' earthquake maps. There are new data from the USGS and UCERF3, which helps us better understand how much seismic risk each area faces. These new updates give ideas about the shakes, fire-following, and liquefaction components, as well as tsunami and landslide sub-peril.
This information and the new model can help us better protect our communities from earthquakes.
Washington State, Earthquake & Flood Insurance Trusted Provider
Do you have any questions/concerns?
We work with multiple carriers for your convenience.
Comprehensive Flood & Earthquake Protection for Your Family's Peace of Mind
Washington & Seattle's Top Earthquake & Flood Insurance Specialists
News & Blogs
Life Insurance After a Heart Attack in Idaho | Coverage Options
Life Insurance After a Heart Attack: Finding Coverage Options in Idaho
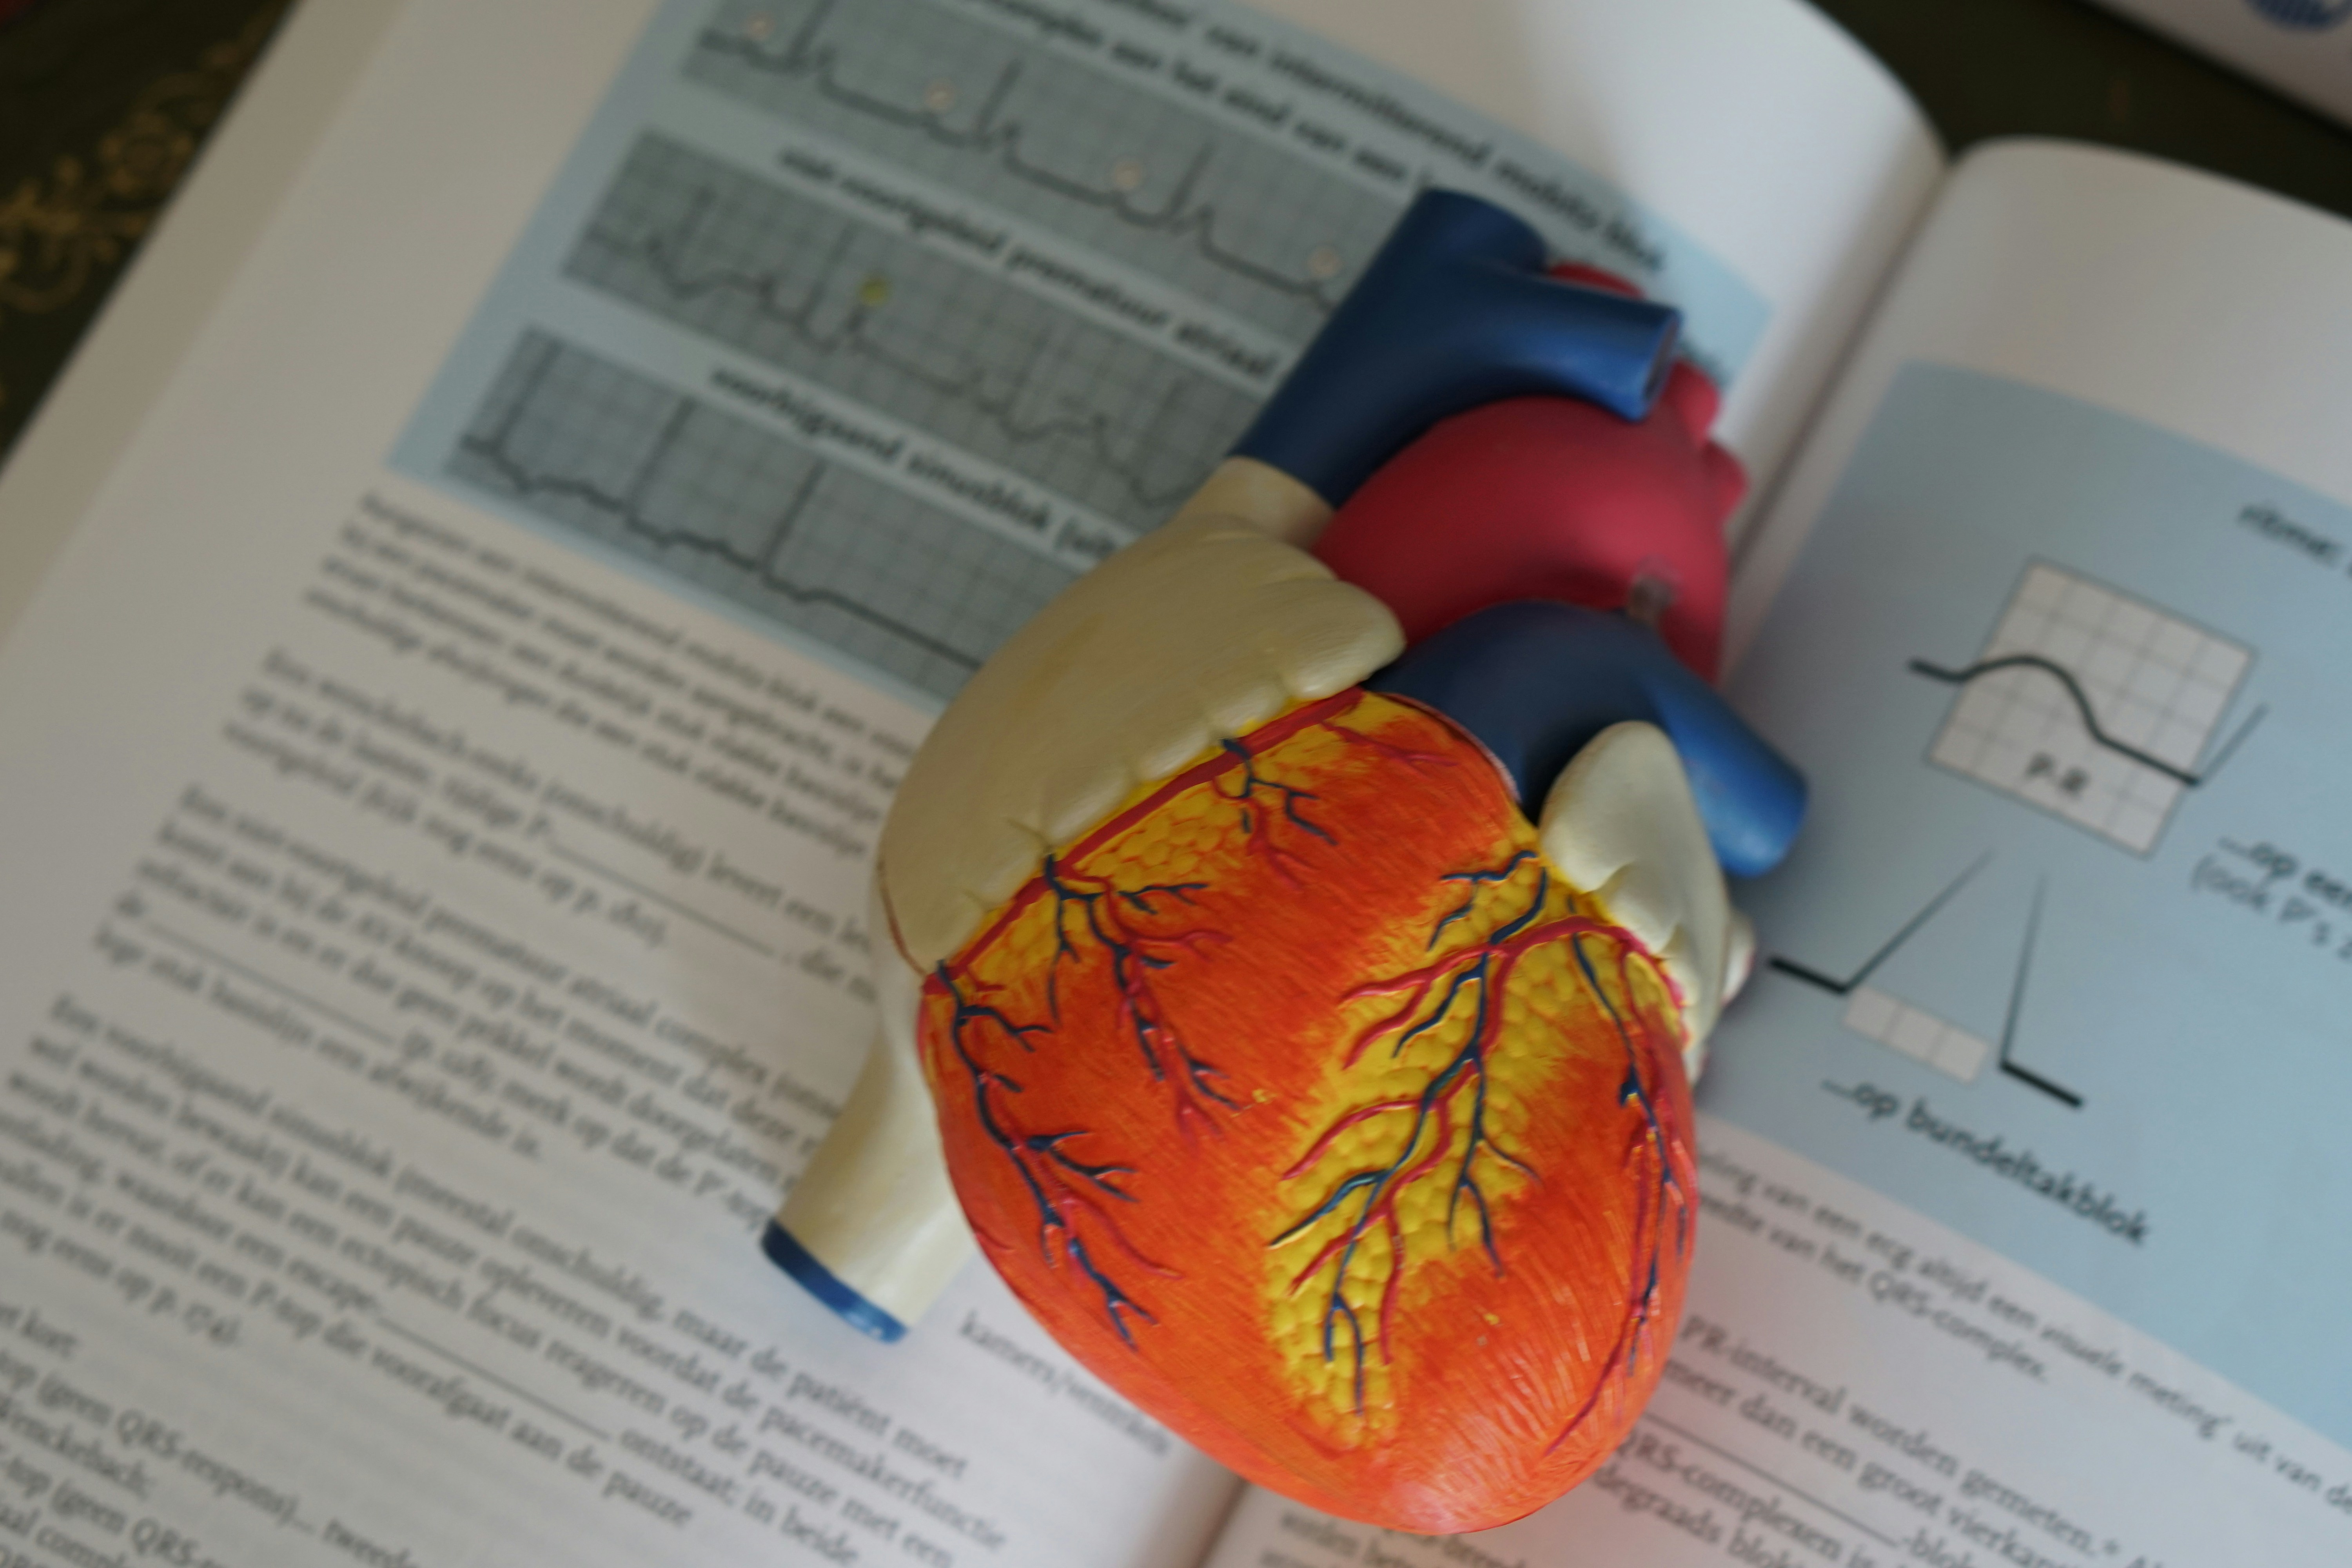
A heart attack can change the way you think about your health, family, and financial future.
After receiving medical care and beginning the recovery process, you may start reviewing responsibilities that you previously overlooked. One important concern may be whether your family has enough financial protection if something unexpected happens.
Unfortunately, applying for life insurance after a heart attack can feel complicated.
You may have concerns about being declined, paying significantly higher premiums, or being limited to smaller policies.
The good news is that a history of a heart attack does not automatically mean every life insurance option is unavailable.
Insurance companies evaluate applicants individually, and their underwriting guidelines can vary.
For Idaho residents, working with an independent agent who understands impaired-risk life insurance may help identify potential coverage opportunities.
Why a Previous Heart Attack Can Affect Life Insurance Eligibility
Life insurance companies evaluate medical history because certain conditions can influence an applicant's risk classification.
A previous heart attack is an important part of that assessment.
However, insurers generally look beyond the diagnosis itself.
They may consider:
When the heart attack occurred.
The treatment received.
Current medical follow-up.
Whether additional cardiovascular conditions exist.
Whether the applicant has other medical conditions.
Age and overall health.
The specific insurance product being requested.
The time since the event can be especially important.
Some insurance companies may have waiting periods or specific eligibility requirements following a cardiovascular event.
Others may evaluate applicants differently depending on their complete medical history.
There is no universal timeline that guarantees acceptance.
That is why applicants should avoid relying on general online statements about when they can qualify.
What Information Should You Prepare Before Applying?
If you are considering life insurance after a heart attack, organizing your medical and financial information can make the process easier.
You may want to prepare:
Medical history: Information about the date of the event, treatment, and subsequent medical care.
Current medications: A list of medications prescribed by your healthcare providers.
Follow-up information: Details about ongoing care and any additional medical recommendations.
Other health conditions: Information about diabetes, high blood pressure, tobacco use, or other medical concerns.
Coverage goals: An estimate of how much financial protection you want.
Budget: An amount you could reasonably maintain each month.
You should never stop or change prescribed treatment to improve your chances of obtaining life insurance.
Your medical care should remain under the direction of your healthcare professionals.
Three Life Insurance Options to Explore After a Heart Attack
Depending on your circumstances and the insurer's underwriting guidelines, several policy types may be worth discussing.
1. Traditional Term Life Insurance
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years.
It may be appropriate for people who want to protect a spouse, children, mortgage, or other financial responsibilities.
Some applicants with a history of cardiovascular problems may qualify for term insurance, depending on their health history and the insurer's requirements.
The available premium and coverage amount will depend on underwriting.
2. Simplified Issue Life Insurance
Simplified issue policies generally use health questions rather than requiring a traditional medical examination.
However, a previous heart attack may affect eligibility.
Some policies have strict restrictions concerning cardiovascular history, so applicants should review the health questions carefully.
This option should not be confused with guaranteed approval.
3. Final Expense or Guaranteed Issue Insurance
If traditional coverage is not available, smaller permanent policies may provide another option.
Final expense insurance is designed primarily to help beneficiaries manage funeral expenses and other smaller obligations.
Guaranteed issue coverage may be available to some applicants who cannot qualify for medically underwritten products.
However, these policies can have smaller benefit amounts, higher premiums relative to coverage, and waiting periods or graded benefits.
Understanding the limitations is essential before making a purchase.
What If You Have More Than One Heart-Related or Medical Concern?
A heart attack may not be the only factor in an insurance company's evaluation.
Some applicants also have high blood pressure, diabetes, elevated cholesterol, or other medical conditions.
The combination of these factors can influence the underwriting decision.
For example, an insurer may evaluate an applicant with a heart attack history and diabetes differently from someone whose medical history involves only one condition.
This does not mean the applicant has no options.
It means the insurance search should account for the entire medical profile.
An independent agent can help identify insurers that may be appropriate for a particular situation.
Why Applying to the Right Carrier Matters
Insurance companies have different underwriting guidelines.
A carrier that is restrictive about one medical condition may not evaluate every applicant the same way as another carrier.
That makes strategic carrier selection important.
Chris Antrim is an independent life insurance agent based in Boise with more than 20 years of experience in health and life insurance.
His website highlights impaired-risk underwriting and access to multiple carriers.
The process involves understanding the applicant's circumstances, reviewing possible policy types, and identifying a realistic application approach.
This is particularly valuable for people who have already been declined or who are unsure whether traditional coverage is still possible.
An independent agent cannot guarantee approval or change an insurance company's medical requirements. However, informed carrier selection can help applicants avoid pursuing unsuitable options.
Should You Wait Before Applying for Life Insurance?
The appropriate timing depends on your medical history and the insurance company's eligibility rules.
Some insurers have specific requirements regarding the amount of time that must pass following a heart attack.
Other factors, such as treatment, recovery, and additional medical concerns, may also affect eligibility.
Before submitting an application, ask which insurers may consider your circumstances and what documentation may be required.
If you are not currently eligible for a particular policy, an agent may be able to explain whether another product is worth investigating or whether waiting and reassessing could be appropriate.
Discuss Your Life Insurance Options With Chris Antrim
A heart attack can make financial planning feel more complicated, but it does not mean you should automatically abandon your search for coverage.
The next step is to understand what options may be available based on your actual medical history.
Chris Antrim helps individuals throughout Boise, Meridian, Eagle, Kuna, Star, Nampa, Caldwell, and other Idaho communities explore life insurance with existing health conditions.
Whether you are considering term life, whole life, final expense, or guaranteed issue coverage, an informed discussion can help you understand the differences.
Call or text (425) 761-0555 to discuss your circumstances and explore possible coverage options.
Visit the life insurance for more information.
Your family's financial protection deserves careful consideration, even when your health history makes the insurance process more challenging.

Affordable Insurance With Personal Service - Local Agents & Brokers
All Rights Reserved | Washington Earthquake & Flood Insurance
Privacy Policy | Disclaimer Terms & Conditions
Contact Us


